
 Windows & doors
 Kitchen remodeling
 Bathroom remodeling
 Home additions & ADU
 Roofing
 Driveway & pavers
 Fence
Free written scope consultation - allowances, timeline, and change-order rules on paper before a single trade is scheduled
Styles & brands we work with
- Kitchen remodeling
- Bathroom remodeling
- Home additions & ADU
- Roofing
- Windows & doors
- Driveway & pavers
- Fence
See the difference
 Before
 After
 Before
 After
 Before
 After
Do Impact Windows Lower Insurance in Miami, FL? The Short Answer
Yes, impact windows lower homeowner insurance premiums in Miami, but only when three documents exist together: a Miami-Dade NOA product approval for the windows, a closed building permit for the installation, and a wind-mitigation inspection report (the OIR-B1-1802 form) completed after the work is done. Most Miami homeowners who installed impact windows and never saw their premium drop are missing the third item, often because the second was never closed. Windows protect the house. Paperwork earns the discount.
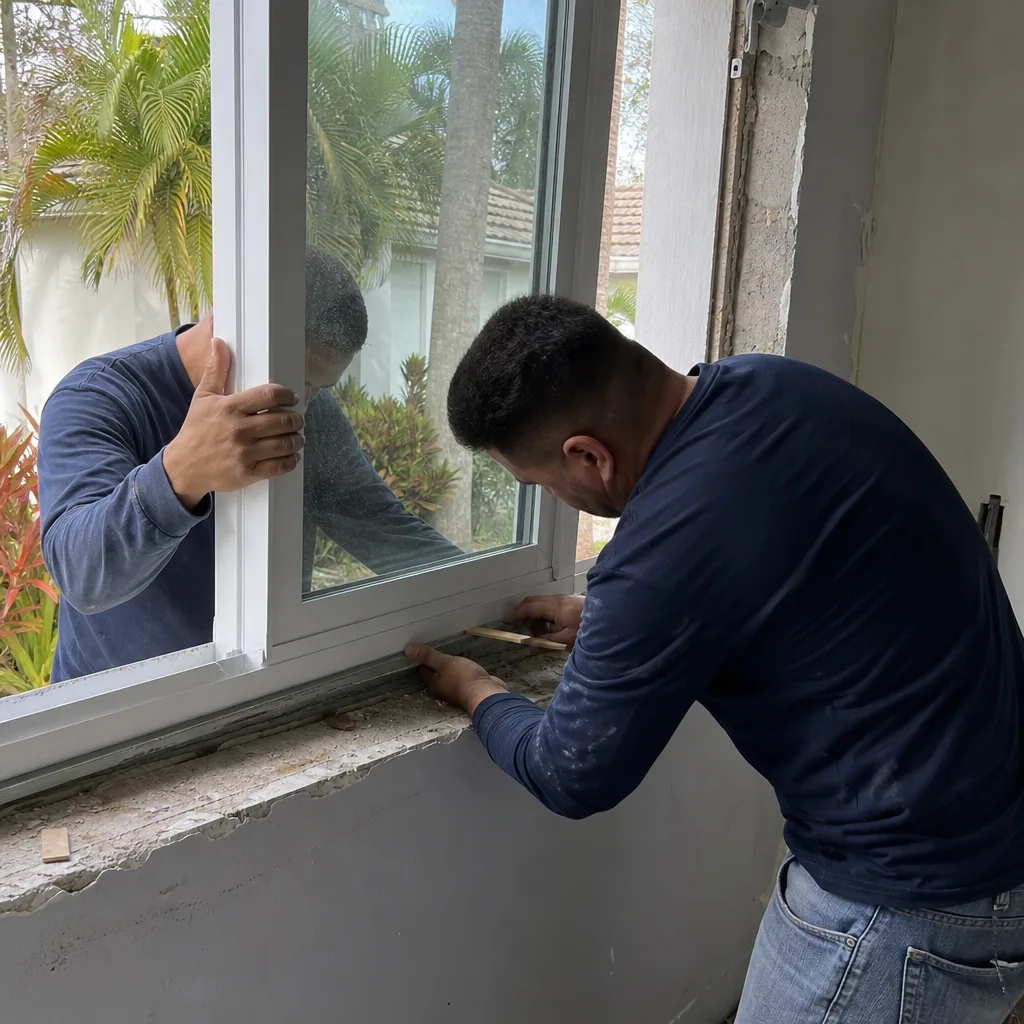
If your windows are in but your premium hasn’t budged, the fix is usually documentation, not replacement. Groundwork Construction Co. of Miami builds the insurance submission package into the job from the start. For a free assessment, call (833) 968-1198.
Why Your Premium Didn’t Move After New Windows
Here’s the scenario we run into constantly. A homeowner in Westchester or a 1950s CBS house off Coral Way spent real money on impact glass a few years back. The windows are sturdy and certified. Then the renewal arrives, and nothing changed.
In almost every case, it’s one of three gaps:
- No closed permit. The installation was never signed off by the building department. A wind-mitigation inspector can’t certify opening protection on openings the county doesn’t show as legally completed, so the OIR-B1-1802 gets filled out with no credit applied.
- No NOA on file. Miami-Dade is the only place in the US with its own product-approval system. Every impact window here must carry a Miami-Dade NOA number, not just a Florida or national approval. If the product approval isn’t documented, the insurer can’t credit the opening.
- No post-installation inspection. The report must be completed after the windows are in. An old inspection from before the upgrade reflects the original, weaker openings.
The windows are real. The savings aren’t, until the paperwork catches up.
How the Wind-Mitigation Credit Actually Works in Miami
Your insurer doesn’t credit impact windows by looking at them. It credits the licensed inspector’s OIR-B1-1802 form and the product approvals attached to it. That form requires a closed building permit and NOA-compliant products to be completed accurately. Skip one and the credit doesn’t apply, no matter how good the glass is.
When everything lines up for full opening protection (impact windows and doors on all openings), Miami-Dade homeowners typically qualify for the maximum wind-mitigation credit in their insurer’s rating schedule. Industry data puts that at 25% to 45% of the wind portion of the premium. On a Miami-area policy, that can work out to roughly $1,000 to $3,000 a year.
A rough look at what full opening protection can do
| Scenario | Typical annual wind-credit range |
|---|---|
| Impact windows only (partial openings covered) | Lower end of the 25%-45% band |
| Full opening protection: impact windows and doors on every opening | Top of the band, often $1,000-$3,000 annually |
| Pre-2002 CBS home upgrading from a weak baseline | Largest relative reduction (steeper % improvement) |
The credit math also differs between carriers. Citizens Insurance, Florida’s insurer of last resort and a common choice across Miami, applies its own rating schedule, and private carriers apply theirs. Some want the OIR form plus invoices; some want the NOA numbers listed. A submission package built for one may miss what the other requires. Groundwork assembles documentation that works for both so you’re not left decoding your insurer’s checklist alone.
Older Miami Homes See the Biggest Premium Drops
Pre-2002 construction homes in Miami get a larger relative credit than post-2002 homes. It’s not a billing quirk. These houses are being upgraded from a lower wind-mitigation baseline, so the percent improvement in the rating is steeper, and the insurer’s algorithm reflects that. A 1960s concrete-block home in Little Havana or Shenandoah with true full opening protection often sees a disproportionately large premium reduction compared to a newer build that already scored well. The dense mix of pre-1970s CBS and unreinforced masonry stock here means a lot of Miami homes are sitting on that older, weaker baseline, which is exactly where the credit pays off most.
Combine the aged housing stock with the 40-Year Recertification law (25 years for buildings near the coast), and Miami construction becomes as much about documented wind-resistance as it is about the building itself. When we plan an impact window project through our Windows & Doors service, the permit and the inspection are steps in the schedule, not a favor you have to chase afterward.
The Paperwork Is Built Into the Job
We treat the insurance submission as part of the project, not an afterthought. On a Groundwork job, we pull the permit, coordinate the wind-mitigation inspection, and hand over the closed-permit documentation and NOA product approvals at completion. You get a package ready to submit to Citizens or a private carrier, and we choose products, such as ES Windows or ECO Window Systems, that carry current Miami-Dade NOA numbers so the inspector can certify them without a fight.
Our technicians have up to 12 years of experience, arrive background-checked and in uniform, and every project is covered by our 730-Day Done Right Promise. If something needs correcting, we make it right. That’s the accountability moving part of a wind-mitigation job needs, because a missed inspection turns into a lost credit year after year. It’s how we run full-scope work from foundation to finish line on projects across our Miami service area and home base.
Common Local Scenarios We See
The 1950s CBS ranch in Westchester. Solid walls, weak original openings. Once full opening protection and a clean OIR form are in place, this is the setup that sees the largest relative premium drop.
The Brickell or Biscayne Boulevard condo. Glassy high-rises already meet impact requirements, so the credit depends on the building’s documentation, not a redo. We tell owners here what the association and insurer actually need before anyone spends money.
The half-finished upgrade. Impact glass on the front, original sliders on the back. Partial opening protection rarely earns the full credit. Closing the gap on the remaining openings is often the cheapest route to the top of the band.
FAQs
Yes, they lower premiums, but only when a closed building permit, Miami-Dade NOA product approvals, and a post-installation wind-mitigation inspection (OIR-B1-1802) all exist. Windows alone don’t move the premium; the documented credit does. Call (833) 968-1198 to have your paperwork checked.
Full opening protection typically captures 25% to 45% of the wind portion of the premium, which on a Miami-area policy can mean roughly $1,000 to $3,000 a year. Pre-2002 CBS homes usually see the larger reductions. Call (833) 968-1198 for an exact quote on the work; estimates are free.
It’s the wind-mitigation inspection report your insurer uses to apply the credit, and it can only be completed accurately when there’s a closed permit and NOA-compliant products for the openings. No closed permit means no certification, and no certification means no credit. Call (833) 968-1198 and we’ll walk through what your job needs.
Sometimes, yes. If the installation is sound but the permit was never closed or the inspection was never done, we can often get the documentation corrected and the credit applied on your next renewal. Worth a look before you spend on replacement. Call (833) 968-1198 to review it.
Ready to Turn Your Windows Into Lower Premiums?
If your impact windows are in but the savings never showed up, the gap is almost always paperwork, not product. If you’d rather have it looked at, Groundwork Construction Co. of Miami offers a no-pressure assessment in Miami: we’ll review the permit status, confirm the NOA coverage, and lay out the path to the credit. Call (833) 968-1198 for a free estimate.
Written by the team at Groundwork Construction Co. of Miami, serving Miami, FL.